Green Finance, Asset Pricing and Market Risk Premia: Where Do We Stand?
Green Finance, Asset Pricing and Market Risk Premia: Where Do We Stand?
Received: 17 July 2026 Revised: 25 August 2026 Accepted: 03 September 2026 Published: 23 September 2026

© 2026 The authors. This is an open access article under the Creative Commons Attribution 4.0 International License (https://creativecommons.org/licenses/by/4.0/).
1. Introduction
This paper investigates whether climate-related preferences and risks constitute a systematically priced factor in financial markets and whether the observed greenium provides evidence of such pricing across sovereign bonds, corporate bonds, and equity markets. The development of green finance has been one of the most important financial breakthroughs in the domain of sustainable finance during the last 20 years. Financial innovation plays a crucial role in financing the adaptation to the consequences of climate change and minimizing damage from climate-related natural disasters. Given that climate change affects people across generations, part of this financing needs to come in the form of debt, which allows for the distribution of the financial burden of climate expenditure across generations. The financial industry is becoming increasingly important in accelerating the transition to sustainability and carbon neutrality, as innovative finance instruments, such as green bonds, allow companies and policymakers to tap broader capital markets to finance Sustainable Development Goal–related projects.
The concept of climate risk pricing refers to the adequate way of incorporating into asset valuations the impact of transition and physical risks stemming from climate change. The former arises from the ongoing shift toward a low-carbon economy, encompassing mitigation and adaptation policies, the development of cleaner technologies, and the consumers and investors evolving behaviours. The latter results from changes in the climate itself, including long-term alterations in average temperatures, weather variability, and the frequency/intensity of extreme climatic events. The important question, from the investors and issuers’ standpoint, is the extent to which climate change risk is (systematically) priced in financial markets. The specific size of the implied risk premium is also relevant for all market participants. Are investors pricing physical risk, transition risk, or both? Recent evidence often suggests that transition risk appears increasingly priced whereas physical risk pricing remains incomplete. This remains an important research frontier question deserving further investigation.
Green assets can fulfil a dual role, satisfying both investors’ standard financial objectives as well as their environmental goals. As a result, investors utility function can benefit from both sources, the traditional financial return accumulation as well as the non-pecuniary externality of positive environmental outcomes associated with their investments. In this extended utility approach, investors internalise the value of the positive externality outcome of their investment strategies. This framework can justify the reason why green assets may command higher prices than comparable, more conventional, assets. It is evident that this framework goes beyond the traditional behavioural finance perspective. As far as the investor is concerned, the value of non-financial benefits can offset the lower financial (expected) returns. This argument applies to a broad spectrum of greener assets, such as bonds, equities, infrastructure, and commodities, in that their expected (risk-adjusted) returns can imply higher prices than those of lesser green (brown) assets. At the same time, increased attention to climate-related risks can raise the rate of discount of long duration assets, potentially reducing bond values and firm worth. According to ref. [1], green bonds and green equities are the most common environmentally oriented investment instruments, oftentimes structured around green indices and replicated through Exchange-Traded Funds (ETFs). However, green investment targets need not lead to larger allocations to greener assets, in that investors’ risk aversion ultimately determines the level of risk exposure that the market can actually bear. This implication highlights the crucial role played by the interaction between risk preferences and goal-oriented utility in the decision process leading to the choice of greener investment [2].
While there are several potential benefits from tapping (sovereign and companies) climate bond financing, an important (pecuniary) benefit for green bond issuers has been that their yields could embed a positive green premium (greenium), that is, a lower yield relative to a conventional bond with similar characteristics (currency, maturity, etc.). Hence, the issuer can realise a greenium issuing a green bond as an alternative to a conventional bond and thereby reducing the burden of interest payments. This concept has drawn significant attention as governments explore green bonds to fund climate and sustainability initiatives, and a growing number of companies are involved in the transition to a more sustainable business model and carbon neutrality. A positive greenium implies investors accept a lower return (higher price) due to the bond’s green label, potentially reflecting factors like high demand from environmental, social, and governance (ESG) focused investors or perceived reputational benefits. Conversely, in theory, one might expect no pricing difference, since green bonds carry the same credit risk and rank pari passu with conventional bonds, or even a negative greenium, given that issuance amounts and liquidity are smaller than those of conventional bonds. The existence of a greenium is thus an important empirical question for the response to the challenges of climate change, with important policy implications: a persistent greenium can lower companies and sovereign financing costs for green projects and signal strong investor appetite for sustainable debt, but it also raises questions about market efficiency and the balance of supply and demand for green assets.
Prior research has studied the greenium and its interaction with several market and fundamental determinants. So far, the results remain somewhat mixed. Some studies seem to confirm that investors are comfortable with earning lower yields for environmentally sustainable bonds with respect to conventional bonds. Other studies find that green and conventional bond yields do not differ if all other characteristics remain equal. Results seem to vary due to differences in sample data, time series periods under of investigation, econometric methodologies, and issuer characteristics. Also, green bond funds remain small and typically underperform their benchmarks.
In the context of green bond markets, the Efficient Market Hypothesis (EMH) implies that information related to the disclosure of risk factors should already be incorporated into green bond prices and their greenium factor 1. Hence, no predictable relationship between risk factors and future green bond yields can be observed if financial market arbitrageurs operate without essential frictions. According to refs. [3,4], green and conventional bond issues for the same issuers, on the same day, do not differ. They conclude that investors show no particular willingness to pay a premium for green bonds. Similarly, ref. [5]’s econometric evidence confirms that the greenium is small at best or even absent in the primary market, as new bond issues are marketed at a small discount to stimulate investors demand for bonds that may be less liquid. In the secondary market, however, they report that green bonds generally trade at relatively higher prices than conventional bonds for the same issuers, thus reflecting a positive greenium.
In the subsequent sections of this paper, we provide a conceptual framework on the climate risk pricing and greenium definitions (Section 2); we will review the issues and evidence of the green premium in the bond market with emphasis on the sovereign sector (Section 3), the corporate bond sector (Section 4), the equity markets (Section 5), with a discussion of the results obtained by a number of studies on the impact of climate risk. In Section 6, we will discuss the importance of the role of investors’ evolving perceptions of climate change in explaining the dynamics of green assets price. We will then delve into the description of econometric methodology and testable hypotheses for estimating asset pricing models with a green risk premium properly included in the set of risk factors and consistent with the latest version of the APT (Asset Pricing Theory; Section 7). Finally, we will conclude the paper by summarising the main findings consistent with our adopted reference asset pricing model, along with some of their implications for green asset markets and prices (Section 8).
2. From Greenium to Climate Risk Pricing: A Conceptual Framework
The growing literature on sustainable finance frequently employs the terms greenium, green risk premium, climate risk premium, and sustainability preference premium interchangeably. While these concepts are related, they refer to distinct economic mechanisms. Failure to distinguish among them can lead to ambiguity in the interpretation of empirical results and may partly explain the heterogeneous evidence reported in the literature. A coherent analytical framework, therefore, requires a clear separation between these different channels through which climate considerations can affect asset prices.
At the most basic level, the greenium is a market-observed price differential associated with green assets. In bond markets, it is typically measured as the yield spread between a green bond and an otherwise comparable conventional bond issued by the same borrower. A positive greenium implies that investors are willing to accept a lower yield, and therefore pay a higher price, for a green-labelled security. The greenium is therefore an observed pricing outcome. It does not, however, identify the underlying economic forces that generate such a pricing differential.
A second concept is the climate risk premium. In standard asset-pricing theory, risk premia compensate investors for bearing systematic risks that cannot be diversified away. Climate change may constitute such a source of systematic risk through two principal channels. The first is physical risk, resulting from the increasing frequency and severity of climate-related events, rising temperatures, water scarcity, and other environmental disruptions. The second is transition risk, arising from the adjustment toward a low-carbon economy through regulation, carbon pricing, technological innovation, changing consumer preferences, and shifting investor attitudes. If climate-related risks are perceived as systematic and financially material, investors should require compensation for holding assets that are particularly exposed to them. In this framework, the higher expected return of carbon-intensive assets relative to greener assets can be interpreted as a climate risk premium. Brown firms may therefore exhibit higher expected returns because investors demand compensation for exposure to future regulatory, technological, litigation, or reputational risks associated with the transition process.
A third concept is the sustainability preference premium, which originates from investors’ non-pecuniary preferences. Recent equilibrium models of sustainable investing suggest that investors derive utility not only from financial returns but also from the environmental characteristics of their portfolios [6]. Under this framework, investors may willingly accept lower expected returns on green assets because holding such assets generates additional utility. The resulting lower expected return is not compensation for lower risk but rather reflects the shadow value investors assign to environmental outcomes. The premium thus arises from preferences rather than from market risk-sharing considerations.
These distinctions imply that the existence of a greenium does not necessarily constitute evidence of climate risk pricing. A positive greenium can emerge even if climate risks are not fully priced, provided that sufficient investor demand exists for sustainable assets. Conversely, climate risks may be priced without generating a sizeable greenium if asset markets simultaneously incorporate offsetting effects such as liquidity premia, issuance costs, or supply constraints. Observed green bond spreads therefore represent the equilibrium outcome of multiple interacting forces rather than a pure measure of climate risk valuation.
More generally, asset pricing implications differ depending on the channel that dominates. Under a pure climate-risk interpretation, greener assets may command higher prices because they provide protection against future climate-related losses and therefore act as hedging instruments. Under a sustainability-preference interpretation, greener assets may be valued more highly because investors assign intrinsic value to environmental outcomes. In practice, both mechanisms are likely to operate simultaneously, making empirical identification challenging.
An additional consideration concerns the dynamic nature of climate-related preferences and risks. Climate policies, technological developments, public awareness, and regulatory frameworks evolve continuously. As a result, both climate risk perceptions and investors’ sustainability preferences are likely to vary over time. The greenium should therefore be viewed as a time-varying equilibrium outcome rather than as a fixed market parameter. This perspective is consistent with recent empirical evidence showing that green premiums tend to widen during periods of heightened climate concern, stronger policy commitment, or increased demand for sustainable assets. Section 7 below illustrates this point. Major policy events such as the Paris Agreement, the launch of the European Green Deal, or shifts in climate-related political commitments have been associated with substantial changes in estimated green risk premia. Such evidence suggests that green asset pricing reflects not only firms’ environmental characteristics but also the evolving credibility of the transition process and investors’ expectations regarding future climate policies.
In light of these considerations, this paper adopts a broad interpretation of climate-related asset pricing. The greenium is viewed as an equilibrium pricing wedge that may incorporate three distinct components: (i) compensation for exposure to climate-related risks, (ii) investors’ sustainability preferences and environmental values, and (iii) market-specific factors such as liquidity, certification, regulatory incentives, and supply-demand imbalances. Understanding the relative importance of these components is essential for assessing whether financial markets are effectively supporting the transition toward a low-carbon economy and whether climate risks are adequately reflected in asset valuations.
This conceptual distinction provides the organising framework for the remainder of the paper. The subsequent sections review the empirical evidence across sovereign bonds, corporate bonds, and equity markets, while the final asset-pricing framework explicitly incorporates climate-related factors as potential determinants of expected returns.
3. The Green Premium and the Bond Market: Issues and Evidence
Green bonds are functionally similar to conventional non-green fixed income securities. The difference is that their prospectus contains a ‘Use of Proceeds’ pledge towards ‘Green’ activities. Green bonds are often structured similarly to traditional “plain vanilla” bonds. Raised funds, however, are earmarked by issuers for contributing towards achieving stated, measurable environmental goals. The purpose of green bonds is to “internalise environmental externalities and adjust risk perceptions” [7]. Environmental goals can be very broad in their scope. They may include climate change mitigation, climate change adaptation, natural resource conservation, biodiversity conservation, pollution prevention, and pollution control. Green bonds allow investors to be exposed to the activities and the (positive) impact of specific projects. Green bond holders, however, get exposure to the credit risk of the issuer rather than to specific projects. The similarities in the mechanics and profile of green bonds suggest that they should be pari-passu with non-green bonds of an identical issuer, seniority, and optionality. This theoretical principle of equivalence between green and brown bonds, also based on the EMH, and the assumed implication of flat pricing, is not always observed in the bond markets. Climate transition bond issuance is still developing and remains at a relatively low level compared to lesser green bonds. The creation of common standards and definitions is a key area for the development of a global sustainable bond market.
The fundamental challenge is isolating the yield difference attributable to the “green” label from other bond characteristics (credit quality, maturity, liquidity, etc.). There are several technical arguments to support the existence of a favourable wedge between green and conventional bond price, denominated in the academic literature ‘greenium’ pricing. This wedge is defined as the difference in yield between green (more broadly, thematic) and conventional bond with similar maturity. The underpinning is that investors are willing to pay extra for a bond with a sustainable impact. There are at least three basic reasons why investors can be prepared to accept a yield discount for holding green bonds:
- (1)
-
a greenium can be a part of the overall discount factor (or the required rate of return) from the investor standpoint. The sustainability factor associated with a green bond is perceived as a credit positive (the issuance of the bond is perceived to improve issuer’ sustainability) which in turn can result in lower overall risk of the issue (issuer), warranting a lower yield (higher price) relative to the conventional yield curve.
- (2)
-
higher demand for green debt in the presence of specific funds mandate investments in sustainable instruments can create excess demand for green assets resulting in higher prices for investors and thereby lower yields.
- (3)
-
the mission value of the underlying investment or the appreciation of its sustainable features (positive environmental externality).
In the literature and market research, there are two common approaches to estimating the greenium. One approach is the matching, or “twin”, bond method (e.g., ref. [3]), which often relies on matching each green bond with an otherwise identical conventional bond issued by the same issuer. Other studies have employed cross-sectional and panel regression analysis (e.g., ref. [8]), in which bond yield spreads or issuance yields, are regressed on a green bond indicator along with controls for maturity, credit rating, liquidity, and other yield determinants. Some recent studies refine this by fitting yield curves (e.g., ref. [9] used a Nelson–Siegel–Svensson yield curve model). A few papers use event studies (e.g., stock price reactions to green bond announcements) to gauge whether issuing a green bond confers value, an indirect way to infer if investors view the financing as favourable. While outside the scope of bond yield itself, such studies (e.g., refs. [10,11]) generally find positive stock market reactions, consistent with a perceived benefit to issuing green debt. Additionally, researchers have started examining related instruments like green loans and sustainability-linked bonds for analogous “sustainability premiums”. These often use similar yield-spread comparisons or matching methods.
The study of ref. [12], one of the first explorations of the green and non-green bond pricing differential based on the outcome of a regression model, discussed four potential explanations for the greenium,
- (1)
-
Supply and demand mismatch for green bond issues relative to their non-green equivalents, suggesting that greenium could be a short-term phenomenon, unsustainable in the long-term as issuers tend towards cheaper funding. This approach recognises green funding as an inherent funding (statistical) arbitrage.
- (2)
-
According to some market participants, the green bond market should trade at tighter spreads to reflect their externalities. The problem with this assertion is that holders of green bonds are not the residual claimants of the environmental benefits, in that the positive impact of green bonds on the environment is enjoyed by the whole society at large and is certainly not confined to the holders of green bonds.
- (3)
-
Tighter green bond spreads may reflect investors’ preferences, in which investors perceive benefits that offset lower cash flows. Such perceived benefits could be ‘psychological benefits’, brand value, influence with regulators and other non-financial gains.
- (4)
-
Green bonds may be inherently less risky or volatile than otherwise similar conventional bonds, rendering tighter spreads appropriate to their risk-adjusted return. Also, holders of green debt—e.g., ‘environment-focused investors’, which are often classified as ‘hold-to-maturity’ investors—trade less frequently green bonds which can imply less price variability, particularly in times of underlying market stress.
In general, according to the evidence reported in ref. [13], “green bonds yield some 15–20 basis points lower returns than comparable conventional bonds in both primary and secondary markets”. This conclusion confirms that investors are willing to accept a lower yield in exchange for holding environmentally sustainable assets. Similarly, ref. [14] studied sovereign green bonds issued in the European Union and, using a matching method, estimated that the average greenium ranged from 3 to 16 bps.
Ref. [15] focuses on the case of the German sovereign bond. Their estimates of a benchmark greenium refer to a time-varying, risk-free, and frictionless taste premium for green securities. It is understood as a model-implied, pure greenium, which is free from any pricing frictions unrelated to the (shadow) value of wide environmental concerns as perceived by bond market participants. In essence, it reflects investors’ green values rather than the financial value of green assets [16].
It is important to point out that the estimated benchmark greenium differs from the simple green yield spread (e.g., the yield spread between green and conventional bonds), in that it is uncorrelated with indicators such as measures of market risk, convenience yield, and temporary demand-supply imbalances. As a difference in discount rates applied to bond cash flows, the greenium should be interpreted as the economic value of a difference in preferences for green vs. conventional assets. The expected green excess return, on the other hand, also incorporates the risk that green preferences themselves can change, which can lead to unexpected inflows into green assets [17]. Not only are the benchmark greenium and expected green excess return different, but, very importantly, they can also have opposite signs, particularly in the short run. More specifically, we should recall that yields are only expected returns from holding bonds to maturity; hence, over shorter holding periods, it is possible for expected returns to diverge from yields, especially for longer-maturity bonds. In fact, ref. [15] estimates that expected green excess returns are often positive, even though the greenium is consistently negative.
Their econometric evidence provides a few key insights into how investors’ green values shape green asset prices: (i) over time, the benchmark greenium widens from 0 to nearly 8 basis points. Hence, greenium exists, and its size is nontrivial, suggesting that green investors are willing to subsidize green projects; (ii) taste premia can have persistent and time-varying effects on asset prices; (iii) Greenium reacts in response to shocks to climate concerns and is usually largest at shorter maturities.
This latter evidence implies an inverted greenium term structure, suggesting that the value of climate concerns is expected to decline over time [6,15,17] 2. As a result, investors seem to be willing to sacrifice financial returns more in the short term than in the long term.
The findings of ref. [15] seem to have several important policy and market implications. The benchmark greenium provides a clearer signal to sovereign issuers willing to issue green bonds in order to broaden support for sustainable finance, in that it reflects the shadow value of environmental concerns. Governments should consider issuing shorter-term green bonds to capture greater subsidies from green investors and thereby save taxpayers money. Last but not least, a risk-free greenium provides a benchmark for pricing riskier green assets, facilitating the issuance of these securities and thereby stimulating private funding of the green transition.
All in all, the empirical evidence seems to confirm the existence of greeniums in the sovereign bond market, although this evidence may not always be so compelling, and its range of estimated values may span a few basis points only. The greenium, however, clearly can work as a signal-sending mechanism which may not necessarily persist in the long term. While issuers could benefit from lowered borrowing costs on sustainable debt, some investors are questioning the rationale behind greeniums—paying extra for a bond with a sustainable label—arguing there may be more effective ways to incentivise issuers to boost their spending on sustainability 3.
Ref. [18] discusses the costs and benefits of sovereign green bond issuance. They mention that the issuance of sovereign green bonds can encourage other issuers to enter the green bond market, as it provides a market benchmark. They also argue that green bonds tend to be issued with long maturities, so refinancing risk is lower, and the benefit could be larger for emerging or less-developed countries with less stable demand for extra-long maturities [19]. Refs. [20,21] estimate that, on average, advanced economy sovereign green bonds have about a 4-bps yield discount relative to similar conventional bonds, while the greenium for emerging market sovereigns (EMs) is larger at roughly 11 bps. This suggests that investors are indeed willing to pay an even greater premium for sovereign green bonds in EMs. Also, refs. [20,21] find that the greenium has grown over time, consistent with a maturing market where investor demand for green assets has intensified. Another insight from the country-level results of refs. [20,21] is that while most countries feature a greenium, a few did not, implying that a green label alone is not always sufficient to guarantee a pricing benefit, and country-specific factors (like investor base or credibility of the green spending plans) likely matter.
Ref. [22]’s estimates confirm the existence of greenium across the European green bond market, which is reckoned at some −4 basis points; however, according to their econometric results, no statistically significant greenium is observed in the UK, France, the Netherlands (green bond) markets, and, in contrast with the evidence of ref. [15], Germany.
According to virtually all the evidence in the literature, the nature of the issuer and the certification of green bonds are key factors in determining the green value premium. More specifically, it is beneficial for issuers to appoint external, independent reviewer(s) to confirm the alignment of their bond (or bond program) with the fundamental components of the Green Bond Principles 4 (GBP). They are broadly recognised and applied in the market. Many external evaluation sources are used in the market. In addition to ratings, issuers seek a Second Party Opinion from institutions with expertise in environmental matters (in general, concerning a compliance assessment with the GBP). They can obtain certification by verifying their green bonds against recognized external environmental assessment standards 5.
4. Green Premium in the Corporate Bond Market
Corporate bonds (issued by private companies) were among the first to carry the green label and constitute a large portion of the green bond market. They span sectors from energy and utilities to financials. A number of studies do find a modest but significant greenium for corporate bonds in certain markets or subsamples. For example, ref. [23] examined 121 green bonds and found that corporate green bonds in their European sample had yields 20–23 basis points (bps) lower than comparable non-green bonds (for non-corporate issuers such as supranational agencies, they found around 14–17 bps lower). Ref. [24] similarly found, using a global sample, that green bonds traded at slightly higher prices (about a few bps yield differences on average) than synthetic conventional equivalents, and he noted this greenium tended to be larger for certain subsets, such as green bonds issued by financial institutions and those with lower credit ratings. Consistent with these findings, ref. [25] conducted a meta-review of studies up to 2019 and reported average greeniums on the order of 1–9 bps.
On the other hand, several studies find little to no greenium for corporate bonds, or only conditional effects. Ref. [10], in a widely cited study of global corporate green bonds from 2013–2018, found no significant yield difference between green and non-green bonds on average and concluded that the main benefit of issuing corporate green bonds is in signalling a firm’s environmental commitment (as evidenced by positive stock reactions and improved environmental performance post-issuance) rather than lowering the cost of debt. Similarly, ref. [8] reports a negligible greenium (around 1 bp) for corporate bonds, implying that green bonds were essentially priced the same as conventional bonds in their sample.
Ref. [26] explicitly compares sovereign versus corporate greeniums globally. They confirm that a greenium exists on average, but report that corporate green bonds exhibit a higher greenium than sovereign green bonds. This result is especially pronounced in developed markets, where greenium was evident for both corporates and sovereigns but larger for corporates. In emerging markets, by contrast, they find that greenium is not universally present or significant.
According to ref. [27], fluctuations in the greenium, as measured on the corporate green bond yields, are closely correlated to momentous shifts in climate change policies. For example, in the months following the 2015 Paris Agreement, the greenium broadened from an average of 2 bps to nearly 15 bps, which accounts for 19.76% of the average yield spread in the sample. Conversely, the election of US President Trump and his subsequent decision to withdraw the US from the Paris Agreement coincided with a period in which the greenium gradually declined and eventually faded. In addition, ref. [27] finds that when natural disasters strike, certified corporate green bonds exhibit a positive return, in stark contrast to the negative performance of conventional corporate bonds.
Ref. [28] analyses secondary-market pricing to capture both cross sectional and time-varying heterogeneity of green and conventional bonds issued between 2014 and 2023 by sovereigns, sovereign-backed agencies, and multilateral development institutions. It finds a small but statistically significant greenium, averaging about 2 basis points for advanced economies and nearly 13 basis points for emerging markets. The greenium is larger for lower-rated issuers and increases when climate transition risks become more salient or when issuers are more vulnerable to climate change. Interaction effects indicate that global awareness of transition risks and domestic climate vulnerability jointly amplify the greenium.
Finally, there is some evidence suggesting that the greenium for corporates appears only under certain conditions. Ref. [29] found that any greenium was concentrated in bonds with external certification or verification (and in bonds issued by public sector entities), whereas uncertified corporate green bonds showed no significant premium. Ref. [30] also found the greenium was not universal: they identified a significant greenium only for large, euro-denominated corporate bonds, whereas smaller corporate issues did not have a clear pricing benefit. This suggests market depth and investor base (the euro green bond market, for instance, has many dedicated ESG investors) can affect outcomes.
5. The Green Premium in the Stock Market
While bond-market studies measure the willingness of investors to accept lower contractual yields, equity-market studies investigate whether firms with superior environmental characteristics command higher valuations or lower expected returns. The equity evidence, therefore, offers a complementary perspective on whether climate-related preferences are embedded in asset prices. As far as the stock market is concerned, the evidence for a green premium is also somewhat mixed. This variety of results across the literature stems in part from different methodologies for identifying the impact of greener assets on stock prices. Asset pricing models differ in terms of mathematical structure, econometric techniques, and the set of variables used in parameter estimation. An interesting contribution is that of ref. [31], which we report in some detail, as his approach has been replicated by a number of studies we discuss in this paper. The STOXX Europe total market index (sample period: 2006–2020) “carbon intensity”, as a measure of “carbon risk”, reflecting how many tons of CO2 a company requires to generate 1 million dollars in revenue, is investigated. Companies included in the sample are arranged into quintiles based on their carbon intensity, with the first quintile (Clean) representing those with the lowest emissions, and the fifth quintile (Dirty) comprising the most polluting companies. An asset pricing model is adopted in order to establish the relationship between stock returns and a number of selected risk factors, such as the overall market performance, the Small Minus Big factor, the Momentum factor, and a specific carbon risk factor. In order to construct the carbon risk factor, a hedge portfolio that takes long positions in stocks with low carbon intensity and short positions in stocks with high carbon intensity is defined. Then, the return of this carbon risk factor is computed based on the performance of four distinct portfolios: small companies with high carbon intensity, small companies with low carbon intensity, large companies with high carbon intensity, and large companies with low carbon intensity. The econometric evidence indicates that less carbon-intensive portfolios provide higher returns compared to more polluting ones. Such evidence implies a monotonic reduction in excess return when moving from the clean to the dirty portfolio.
Ref. [32] uses a model based on the Capital Asset Pricing Model (CAPM) methodology with specific factors added. More specifically, the difference between stock returns and the risk-free rate is examined, incorporating traditional Fama and French market style factors. Two new climate risk factors are introduced: the Dirty Minus Clean (DMC) factor, a proxy for carbon risk (a long portfolio in the dirtiest stocks and short in the cleanest ones), and the Climate Risk Factor (Worst Minus Best factor), representing the difference in stock returns between the 22 companies with the worst scores and the 18 companies with the best carbon scores. The study, based on a sample of US stocks from 2005 to 2017, concludes that investing in carbon-intensive and non-sustainable companies leads to higher expected returns. This result is consistent with the concept of an implied green risk premium and the assertion that investing in carbon-intensive stocks is more profitable than carbon-light stocks (albeit riskier).
Ref. [33] estimates a model of stock returns for Germany, the largest economy in Europe and responsible for a significant share of the EU’s carbon emissions. They analyse the performance differential between companies that received free carbon emission allowances and those that did not; it can be argued that the “carbon premium” exists if the companies that received these allowances outperformed the others. The authors find that the carbon premium exists, is relatively high, and is statistically significant (some 17 percentage points). The sample period for the estimated parameters goes from 2003 to 2009, which is the period when the market held the view that carbon-emitting companies would receive carbon allowances for free. The econometric evidence supported the conclusion that companies that received free emission allowances outperformed those that did not.
Ref. [17] analyses how the past performance of green assets impacts future performance. Their equilibrium model predicts that green assets should have lower expected returns compared to brown assets for two reasons: (i) investors have “green” preferences (e.g., they choose greener assets other things being equal); (ii) green assets are perceived as better hedges against climate risk. However, green assets may achieve higher realized returns when investor demand unexpectedly shifts towards greener investment opportunities. Thus, investors’ demand for greener assets can increase, directly boosting their prices; alternatively, consumer demand for sustainable products may strengthen—perhaps due to environmental regulations—leading to increased profits for green companies and thus higher stock prices. Similarly, investor demand for brown assets or consumer demand for such products may decline, again causing green stocks to outperform.
Ref. [17] argues that high realized returns do not always imply high expected returns. More specifically, it is shown that the outperformance of a Green Minus Brown (GMB) portfolio fades once the effects of unexpected increases in climate concerns are removed (the equity greenium is defined as the expected return of the GMB portfolio). This result implies that green stocks outperform brown ones when concerns about climate change increase.
Ref. [34], using a sample of global stocks from January 2010 to December 2017, finds no evidence of a risk premium associated with carbon risk. In their sample period, “brown” companies had, on average, worse performance than greener companies. In performing a set of cross-sectional regressions, they find that the BMG (Brown minus Green) factor is not statistically significant, namely, there is no evidence of a risk premium associated with carbon risk. They argue that carbon risk may not be priced because investors are unable to adequately predict or quantify it.
Ref. [35] studies the greenium in the European stock market over a period of five years (sample period: July-2018 to June-2023). They compute total Return, Standard Deviation, and Sharpe Ratio for sustainable and non-sustainable portfolios, based on both ESG scores and Environmental Pillar Score (E-scores) provided by Refinitiv 6, obtained from the EuroSTOXX 600. They notice that, more often than not, the returns of the brown portfolio exceed those of the green portfolio. Again, this result is consistent with the presence of a green premium and, more generally, a sustainability premium in EU stock market prices. Their results (based on the E-score) show a statistically significant green premium of 1.17%. Similarly, portfolios based on the ESG score show a statistically significant sustainability premium of 2.20%. All in all, less sustainable portfolios tend to generate higher risk-adjusted returns than more sustainable ones, suggesting that sustainability significantly affects expected (risk-adjusted) returns for investors.
These results are broadly in line with those of the study of ref. [36] conducted on the same European stock index (EuroSTOXX 600), albeit on a different sample data (January 2010 to February 2020), again using the ESG score, and E-score. Their evidence confirms the existence of a green premium, as portfolios with lower ESG or E scores achieved statistically significant excess returns greater than those of more sustainable portfolios. Specifically, the brown portfolio (low E-score) showed a positive excess return after the Paris Agreement (0.8847 percent; significant at 5%). Also, portfolios with low ESG scores had positive abnormal returns (Jensen-alpha equal to 0.58 percent; significant at 5%) even before the Paris Agreement. The authors noted that for portfolios with higher E and ESG scores, the estimated regression intercept is not statistically significant. As a result, they argue that there are no abnormal returns for more sustainable companies.
Similarly, ref. [37] analysed European stocks using the E-score and emissions intensity data obtained from Bloomberg. This study employs individual stock returns to examine the evolution of the risk premium linked to firms’ carbon emissions and environmental transparency (e.g., greenium). They extend their earlier work by applying a more sophisticated, time-varying conditional asset pricing model to a larger, unbalanced panel of monthly (European) stock returns (sample period: 2006–2020). This updated framework retains the same greenness and transparency factor for their factor model used in their previous work (see Section 5 below for more details). The study shows that the greenium can vary over time in response to policy developments and market conditions. According to their econometric evidence, green portfolios have lower returns, on average, than brown portfolios. Thus, high emissions companies tend to outperform those with lower emissions. Specifically, the positive and significant Jensen-alpha of brown portfolios relative to the CAPM, 3Fund-Fama French, and Carhart models suggests that brown portfolios tend to generate additional returns that standard style risk factors cannot explain. Green portfolios also exhibit a positive Jensen-alpha value, but generally lower than lesser green companies. Their own computed measure of “greenness and transparency factor”—the difference between the returns of the green portfolio and those of the brown portfolio—yields negative excess returns equal to 0.5% on average. This result shows that less sustainable companies yield returns that are 50 bps higher than those of green companies. The econometric study achieves a fairly high explanatory power (R2 values for the cross-section of stock returns range between 0.88 and 0.94) for their extended factor model, providing a more comprehensive empirical framework than other, less recent papers. Their results confirm the evidence, also highlighted by other authors, that investors’ preferences evolve with the perceived credibility of the low-carbon transition.
Ref. [38] explores the risk and return dynamics of sustainable investment strategies in the euro-area equity market. Their econometric analysis focuses on a set of green stock market indices (sample data 2013–2023 or shorter, according to data availability) and appears to reveal that the ex-post return differential is not significant after controlling for the standard financial risk factors of the Fama-French stock price model. This holds true for investment strategies that hinge on climate change objectives, as well as for strategies that have a broader ESG focus. Thus, these results seem to depart from the empirical evidence for the United States [17,39] and European equity markets, where a statistically significant, although contained, preference premium has been documented in a number of studies, as summarised in this paper. Such departure seems to depend, at least in part, on a different identification method for isolating the greeniun in their regression analysis of the return differential. In essence, they regress the return differential of sustainable indices relative to the market index on a set of standard style risk factors and, inferring from the statistical insignificance of the constant terms in their regressions (Jensen-alpha), conclude that there is no other possible systematic risk factor, including a green risk premium. Unlike the methodology of other studies (see the next section for further details), this testing procedure does not verify directly if a (properly constructed) green risk factor is systematically priced at the (micro) level of individual equity, separately from other (included in the regression) systematic risk factors. Namely, it does not provide a direct test of a statistically significant factor loading for a properly constructed green risk factor—e.g., econometric testing for a statistically significant “green-beta”—after controlling for the standard Fama and French style risk factors.
6. Time-Varying Climate Risk and Investors’ Perceptions
An important strand of the recent climate-finance literature argues that climate-related risks are not only reflected in firms’ environmental characteristics but are also embodied in investors’ evolving perceptions of climate change. In this context, measures of climate news, investor attention, and climate sentiment have emerged as valuable indicators for explaining the time-varying nature of climate-related risk premia. Ref. [40] provides one of the strongest bridges between the traditional asset-pricing literature and the emerging field of climate finance, because it explicitly treats climate concerns as a systematic source of risk that can be measured through climate-related news. This seminal contribution introduces a framework for measuring and hedging climate risk through a climate-news factor. Their central argument is that climate change generates a pervasive source of systematic risk that simultaneously affects a broad cross-section of assets. Unlike firm-specific environmental indicators, climate news captures changes in investors’ beliefs regarding future climate-related developments, including regulatory initiatives, technological progress, environmental policies, transition costs, and the public perception of climate change. The authors construct a climate-news indicator derived from textual analysis of major news sources and identify periods in which public attention to climate-related issues intensifies. Variations in climate-news intensity are interpreted as shocks to climate concerns and are used to investigate whether stock prices react differentially according to firms’ exposure to climate risk. The underlying intuition is that unexpected increases in climate concerns should benefit firms perceived as less vulnerable to the transition towards a low-carbon economy while adversely affecting firms whose business models depend heavily on fossil fuels or carbon-intensive activities.
Based on this framework, ref. [40] constructs a climate-hedging portfolio designed to perform well when climate concerns unexpectedly increase. The portfolio takes long positions in firms that benefit from adverse climate news and short positions in firms that suffer from such developments. Returns on this portfolio provide a market-based measure of climate-risk exposure and can therefore be interpreted as a climate-risk factor in asset-pricing models.
The relevance of this approach extends beyond the measurement of climate risk. Climate-news indicators can also be interpreted as proxies for investors’ attention to environmental issues. In financial markets, attention mechanisms play a crucial role because investors do not continuously process all available information. Instead, they often react to salient events and narratives. Major climate-related events, including international agreements, extreme weather episodes, changes in carbon-pricing policies, or high-profile environmental campaigns, can trigger significant shifts in investor attention and portfolio allocations. Consequently, climate-news indicators capture an important behavioural dimension of sustainable investing that complements traditional risk-based explanations.
The concept of climate attention is closely related to the notion of transition-risk sentiment. Transition risk refers to the economic and financial consequences of the shift towards a low-carbon economy. These consequences arise from changes in environmental regulation, technological innovation, consumer behaviour, litigation risks, and evolving market expectations. Transition-risk sentiment can therefore be defined as the collective perception among investors regarding the speed, credibility, and economic consequences of the transition process.
From an asset-pricing perspective, climate attention and transition-risk sentiment can affect expected returns through several channels. First, heightened climate concerns may increase demand for environmentally sustainable assets, thereby compressing their expected returns and generating a stronger greenium. Second, changes in climate sentiment may alter expectations regarding future cash flows, particularly for firms operating in carbon-intensive sectors. Third, increasing climate concerns can change discount rates by affecting investors’ assessment of long-term risks. As a result, movements in climate-related sentiment may influence both the level and the term structure of climate-related risk premia.
The empirical evidence, as illustrated in Section 5, appears broadly consistent with these mechanisms. Ref. [17] shows that much of the historical outperformance of green stocks can be attributed to unexpected increases in climate concerns rather than to permanently higher expected returns. Similarly, ref. [37] finds that the estimated greenium varies over time and responds significantly to indicators of climate sentiment, commodity prices, and market uncertainty. These findings suggest that investor preferences for sustainable assets are not static but evolve in response to changing perceptions of climate risk and transition opportunities.
Ref. [41]’s empirical evidence on the interaction between macroeconomic regimes (e.g., high vs. low inflation cycles) and investor sensitivity to climate risk in green bonds reinforces the argument that the greenium and climate risk pricing are highly contingent on macroeconomic stability and regime shifts 7. In particular, they show that under inflationary pressures, investors may treat green corporate bonds differently—where climate risk negatively impacts valuations due to hedging constraints—whereas during low-inflation regimes, investors respond positively to climate risk factors. During periods of high inflationary pressures, investors exhibit behaviour towards green bonds that is similar to their behaviour towards stocks. The transition from a high to a low inflation period leads to a change in investors sensitivity in that an increase in climate risk leads to higher valuations of green corporate bonds, possibly because these bonds are perceived as a tool to mitigate climate impact. All in all, macroeconomic conditions and inflationary regimes moderate investor behaviour toward green assets.
The incorporation of climate news factors and macroeconomic conditions into asset-pricing models represents an important conceptual extension of traditional multifactor frameworks. In addition to standard risk factors such as market, size, value, and momentum, climate-news indicators can be viewed as state variables influencing expected returns through their effect on both climate-risk perceptions and investors’ sustainability preferences. Consequently, climate-news variables help explain why the greenium does not appear as a constant feature of financial markets but rather as a time-varying phenomenon reflecting the interaction between environmental concerns, policy developments, and investor behaviour.
From a policy perspective, these findings imply that the pricing of climate-related assets depends not only on firms’ environmental performance but also on the credibility of climate policies and the stability of the low-carbon transition. Policy announcements, international climate agreements, carbon-pricing initiatives, and sustainability disclosure requirements can therefore influence asset prices through their impact on climate-news dynamics and transition-risk sentiment. In this sense, climate-news factors provide a valuable link between environmental policy, investor behaviour, and the evolution of green financial markets.
As we will see in the next Section 7, climate-news indicators and transition-risk sentiment may be regarded as conditioning variables belonging to the investors information set as key drivers of the time-varying green risk.
7. Asset Pricing Model and Green Factor Premium Estimates
There is no solid, full consensus as yet whether financial markets are adequately pricing climate risk. Also, how to measure its impact on asset valuation is still open to debate. With regard to climate transition risk, the evidence is still quite mixed on whether a green risk premium is a persistent component of green asset prices. It can be argued that investors’ attitudes toward green or carbon-intensive assets may change over time. Such variability could explain why quite a few studies show differences in their empirical results while focusing on different sample periods, market data and events. While most of the studies examining the greenium are based on bond yields, testing “green” stocks on equity markets also provides valuable information. The same argument applies for other asset classes as well as alternative investment strategies based on sustainable asset holdings.
The currently proposed standard greenium econometric model relies on a single GMB factor embedded into a standard Fama-French 3-factors asset pricing factor model such as
| ```latex{R}_{t}=\alpha +{\beta }_{m}{MKT}_{t}+{\beta }_{s}{SMB}_{t}+{\beta }_{v}{HML}_{t}+{\beta }_{c}{Climate}_{t}+{\varepsilon }_{t} \,(^*)``` |
where, $${R}_{t}$$ denotes the individual stock (in excess of the risk-free rate) returns, $$\left({MKT}_{t},{SMB}_{t},{HML}_{t}\right)$$ the set of standard Fama-French style factors and $$\left({\beta }_{m},{\beta }_{s},{\beta }_{v}\right)$$ the respective factor loadings; $$\alpha$$ is a measure of extra-performance not accounted for by the risk factors entering the model, and $${\varepsilon }_{t}$$ an IID (zero-mean and constant variance) stochastic disturbance. The climate risk factor itself, $${Climate}_{t}$$, includes several variables, such as emissions intensity, climate sentiment, transition risk, physical risk exposure, corporate transparency; its factor loading, $${\beta }_{c}$$, plays the role of “climate” beta. Climate risk is (systematically) priced if the estimated climate beta, $${\beta }_{c}$$, is statistically significant and the product, $${\beta }_{c}{Climate}_{t}$$, can be interpreted as a risk-premium (e.g., greenium). Such risk premium reflects the fact that firms can differ in their exposure to carbon pricing shocks, regulatory shocks, climate news shocks.
In line with theoretical models explaining investors’ “taste for sustainability”, relaxing the assumption of a constant greenium by introducing an asset-pricing model with a factor structure in which risk premia are time varying can account for the mixed results found by a number of studies. In particular, the model should include time-varying risk factors—among them, a “green” risk factor. Thus, estimating the green premium should bring together an advanced concept of the ‘green factor’ and a state-of-the-art conditional asset-pricing model. This reference (green-based) asset pricing model draws from [37,42], which relies on an advanced asset-pricing model for the excess returns of individual stock based on a set of (linear) risk factors, including a ‘greenness and transparency’ factor. This framework allows us to investigate the drivers of individual stock returns by testing a set of candidate explanatory variables and risk factors, including sentiment and volatility indicators, as well as relevant commodity prices.
In the exposition of our reference asset pricing model for the proper testing of the presence of a greenium, we follow very closely [37,43]. We assume that an approximate factor structure for excess returns exists, combined with the absence of arbitrage opportunities to obtain asset pricing restrictions. In essence, we adhere to the Arbitrage Pricing Theory (APT) model extended to the presence of a green risk factor among the asset prices fundamental drivers. Let us define the excess return on asset, i = 1, 2, …, n at time t = 1, 2, …, T as
where ri,t is the log-return and rf,t is the risk-free return. We follow the theoretical framework of [43] in the exposition of the factor model and restrictions. In particular, the excess return $${R}_{i,t}$$ satisfies the following linear factor model:
where $${f}_{t}$$ is a vector of K observable systematic factors. The constant $${a}_{i,t}$$ and factor loadings $${b}_{i,t}^{\prime}$$ vary over time. The error term $${\varepsilon }_{i,t}$$ is such that
where $${\mathcal{F}}_{t-1}$$ denotes the lagged information set. The approximate factor structure holds for the variance-covariance of the error terms, that is,
with bounded largest eigenvalue (see e.g., ref. [44]). Under no-arbitrage opportunities, the following parameter restriction holds:
where $${\nu }_{t}$$ is a vector of K parameter. The parameter restriction in Equation (5) can also be written as
with,
Risk premia result from the sum of two components, namely, the conditional expectation of the factor, $$E\left[{f}_{t}|{\mathcal{F}}_{t-1}\right]$$, and the process $${\nu }_{t}$$ which captures (expected) market imperfections and frictions.
The conditioning information $${\mathcal{F}}_{t-1}$$ contains the vector $${Z}_{t-1}$$ of p lagged instruments common to all stocks, and vector $${Z}_{i,t-1}$$ of q lagged characteristics specific to stock i. Vector $${Z}_{t-1}$$ may include the constant term, past observations of the factors, and some additional variables such as macroeconomic variables. The vector $${Z}_{i,t-1}$$ may include past observations of firm characteristics and stock returns. Equation (6) and Equation (7) show that expected excess returns of individual stocks are driven by the K-vector of risk premia, $${\lambda }_{t}$$, times the vector of factor loadings, $${b}_{i,t}^{\prime}$$.
Climate risk can affect almost all assets, which can then be priced by financial markets participants. Hence, the set of observable factors, $${f}_{t}$$, also includes the greenness and transparency factor defined as follows,
where $${f}_{t}^{GMB}$$can be defined as a pervasive risk factor (see e.g., [6,40]). We call greenium the risk premium associated with both the greenness and transparency factor combined, denoted $${f}_{t}^{GMB}$$. By construction, the green risk premium results from the sum of two components, namely, the conditional expectation of the green factor, $$E\left[{f}_{t}^{GMB}|{\mathcal{F}}_{t-1}\right]$$, and the process $${\nu }_{t}^{GMB}$$ which captures the associated market imperfections and frictions,
More specifically, a portfolio that hedges against climate risk adopts a long position on a greener and more transparent index portfolio of stocks, $${r}_{t}^{G}$$ and a short position on an index portfolio of high-carbon assets, $${r}_{t}^{B}$$, both of them are suitably constructed. Thus, a positive factor loading associated to the greenness and transparency factor, $${f}_{t}^{GMB}$$,
can signal a lower (risk-adjusted) expected return if
Namely, when a portfolio of greener and more transparent assets is expected to underperform a portfolio of lesser green and less transparent portfolio of assets; by contrast, a negative factor loading, $${b}_{i,t}^{GMB}$$, would imply a greater (risk-adjusted) expected return.
To obtain a workable version model for econometric estimation, we restrict the dynamics of the factor loadings $${b}_{i,t}$$ to be a linear function of the set of variables, $${Z}_{t-1}$$ and $${Z}_{i,t-1}$$,
Moreover, we assume that the vector of risk premia $${\lambda }_{t}$$ are a linear function of lagged common (conditioning) variables, $${Z}_{t-1}$$, that is
and specify the conditional expectation of the set of factors as,
From these specifications and using the asset-pricing restriction in Equation (2), Equation (3), Equation (4), Equation (5), Equation (6), Equation (7), Equation (8) and Equation (9), the econometric model can be expressed as,
where $${x}_{i,t}^{\prime}=\left({x}_{1,i,t}^{\prime},{x}_{2,i,t}^{\prime}\right)$$ involves the cross-terms of common and asset-specific instruments, and observable factors, and has dimension d = d1 + d2, with d1 = p (p + 1)/2 and d2 = K(p + q). The model (15) maintains a linear structure as far parameters’ estimation is concerned. The regressors $${x}_{1,i,t}^{\prime}$$ of dimension d1 of dimension d2 include only predetermined as quadratic transformation of $$\left({Z}_{t-1},{Z}_{i,t-1}\right)$$ and regressors $${x}_{2,i,t}^{\prime}=\left({f}_{t}⨂{Z}_{t-1},{{f}_{t}⨂Z}_{i,t-1}\right)$$. The time-invariant parameters $${\beta }_{i}={\left({\beta }_{1,i}^{\prime},{\beta }_{2,i}^{\prime}\right)}^{\prime}$$ are unconditional transformations of constant matrices $$\left({B}_{i},{C}_{i},\mathrm{\Lambda },\mathrm{F}\right)$$; further details on the structure of regressors matrix $${x}_{i,t}^{\prime}$$ and parameters vector $${\beta }_{i}$$ can be found in ref. [37].
Risk premia can be estimated based on the baseline specification of Equation (15), along with the set of loading parameters for the observable factors, $${\beta }_{i}$$, using individual stocks, as in ref. [37]’s study for a cross-section of European stock returns. This model can deal with unbalanced panels [43], hence allowing to estimate risk parameters on individual stocks rather than portfolios of stocks or indices, while exploiting the time-series dimension for the risk factors, which can shed light on the determinants of the greenium’s dynamics. Parameters of Equation (15) can be estimated by Ordinary Least Square (OLS), or other more sophisticated methods, accordingly.
Greenium drivers over time can be further identified as follows. Let us consider the following simple linear dynamic model [37],
where $${\lambda }_{t-1}^{GMB}$$ captures the persistence of the greenium time series, and $${X}_{t-1}$$ is the potential set of variables of interest as additional drivers.
According to the evidence reported in ref. [37], different channels may drive the greenium time-varying profile, a wide range of variables can be included in $${X}_{t-1}$$, including fossil fuels (coal and oil), all critical minerals for clean energy technologies, financial market volatility, (market-based) economic sentiment index for the European Union, and the negative climate sentiment index defined in ref. [40], which captures public attention and sentiment toward climate change based on news.
Regression results, assuming Gaussian innovations and accounting for heteroscedasticity (as reported by ref. [37]), are obtained from the standard ordinary least squares (OLS) method. They confirm that the candidate’s explanatory variable coefficients, $$\left({\phi }_{0},{\phi }_{1},{\phi }_{2}\right)$$, are statistically significant. The estimated value of $${\phi }_{1}$$ close to 0.95, is consistent with a (slow) convergence to a non-zero green premium value in the long-run and its ample fluctuations in the short run.
The outcome of the simulated greenium based on the parameter estimates of Equation (16) is reported in Figure 1. It turns out that investors “taste for green” clearly appears to change over time, namely, investors’ preferences for greener and more transparent companies (and public sector assets) are definitely time-varying. More specifically, when the economy seems to be struggling to shift toward low-carbon intensity, as may be signalled (for example) by increases in relevant commodity prices, then investors’ tastes become less green, as high-carbon assets are perceived as less risky. By contrast, in periods of market turmoil and a worsening economic outlook, investors tend to go green. The latter result seems to be consistent with the notion that greener stocks can function as a safer-heaven than brown and less transparent stocks.
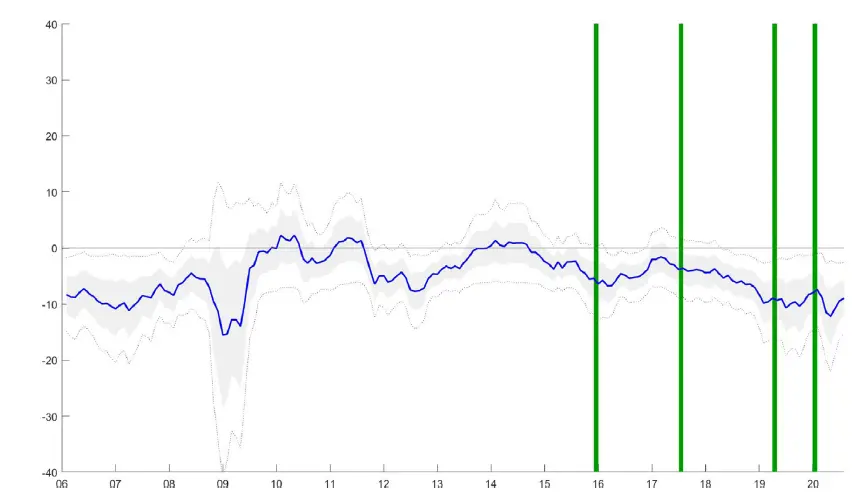
Figure 1. Time-varying estimates of the greenium. Evolution over time of the annualized risk premium estimated from a CAPM including the greenness and transparency factor. Dotted lines and light-shaded areas correspond to the pointwise confidence intervals at the 95% and 68% levels, respectively. The green vertical lines denote, in chronological order, the Paris Agreement, the U.S. withdrawal from the Paris Agreement, the first global climate strike, and the launch of the European Green Deal. Source: [37], p. 7.
The evidence on time-varying grenium has been confirmed by recent empirical developments on adapting multi-factor bond pricing frameworks—e.g., expanding classic [45] stock and bond common risk factor model—to price green corporate bonds by simultaneously incorporating climate risk factors and financial volatility risk factors. In particular, ref. [39] develops a novel five-factor pricing model for green corporate bonds that explicitly integrates a volatility factor (VF), default risk factor (DRF), term structure factor (TERM), market factor (MKT), and a physical climate risk factor (CRF). Their model empirical implementation demonstrates the importance of macroeconomic regime changes in driving corporate bond investors’ response to climate risk. Under inflationary regimes, increased climate risk negatively affects green corporate bond valuations, while volatility risk premia become insignificant. Conversely, during non-inflationary periods, investors respond positively to increasing climate risk and decreasing volatility risk. The regime shifts are captured via a Markov-Switching regime framework.
However, we should acknowledge that linear factor models, such as Equation (15) and Equation (16), are not necessarily in their best position to capture the nonlinear and adaptive interactions between physical and transition risks vs. investor sentiment adjustment over time. Discovering these nonlinear correlations may require the applications of more suitable techniques, such as machine learning or other form of non-linear statistics [46], in that linear approaches may overfit the training data and fail to generalise to unseen sample data.
As linearity may be a too restrictive assumption in mapping from stock characteristics to factor loadings, we can adopt ref. [47] methodology to address this problem by replacing the linear mapping with a neural network structural model, such as
where function g(.) denotes, in the Machine Learning jargon, a Multilayer Perceptron (MLP 8), to estimate risk factors jointly with loadings via an autoencoder objective. The goal of extension (17) would be to construct a nonlinear, characteristic driven factor model that achieves smaller out-of-sample pricing errors than its linear predecessors. However, the economic interpretability of the extended non-linear model (17) should be the next, immediate challenge to tackle, in that minimising pricing errors is not per se sufficient to identify the drivers of forward covariance market prediction as a distinct, albeit harder, objective, shedding light on the sources of time-varying risk premia. Non-linear models can account for higher-order temporal structures and structural discontinuities in the greenium time series, while capturing average dynamics and (at least) some short-term time dependencies. This area of investigation is one of the future directions of research that seems to be promising for improving the estimates of implied greenium in asset prices.
8. Concluding Remarks
We reviewed the evidence of green premium in asset markets across jurisdictions in developed and (some) emerging markets. All in all, the estimated greenium is more often than not statistically significant, albeit its size is relatively small. However, it should be recalled that, as a result of the long-term implications of the climate and physical risk transition, even a few basis points of difference in the discount rate can have a tangible impact on long-duration asset values. This is why it should not be discarded easily as a flimsy outcome of academic research, with little or no practical relevance for investors, issuers, and policymakers.
Evidence increasingly supports the existence of a greenium, but the greenium should not be interpreted as a single, stable parameter. Rather, it reflects the interaction of climate risk, investor sustainability preferences, policy credibility, market structure, certification quality, and macroeconomic conditions. Moreover, the greenium can react to shocks to climate concerns and is often larger at shorter maturities. Such an inverted term structure implies that the value of climate concerns is expected to decline over time. Thus, investors are prepared to sacrifice financial returns more in the short term than in the long term. This may reflect some heterogeneity across investors sensitivity to return in the long-run vs. the short-run, or the conviction the in the long run the distinction between green and brown asset should gradually fade in that all assets become “green” only.
Based on the evidence of academic and institutional literature, we presented key insights into how investors’ green values shape green asset prices. We show that over time the greenium can widen from 0 up to nearly 20 basis points for long duration assets. This indicates that the greenium exists and its size is nontrivial, suggesting that green investors are willing to subsidize green projects. The broader implication is that “taste-related (preference)” risk premia can have persistent and time-varying effects on asset prices, green and brown.
Green bonds issued by the public sector display a more consistent pattern in the estimated risk premium level across markets and jurisdictions, possibly with a greater size for emerging market debt. Grenium appears to be clearly time-varying for developed stock markets, with an average level oftentimes greater than the estimates for the corporate bond market.
Despite the by now abundant and growing evidence on the performance of green and sustainable corporates, however, no full solid consensus has yet been reached in the (mostly academic) asset pricing literature about the relative performance of green assets, or on environmental risk being a priced (macro) systematic risk factor. This lack of consensus appears to be more evident for green risk factor premia in the (publicly traded) equity market. True, quite a few studies find that green stocks are, on average, underperforming the broad market. However, the noisy character of the stock market can be a challenge for isolating the embedded composition of risk premia identifying the genuine drivers of the cross-assets performance differential. An adequate asset pricing model, sophisticated econometric machinery, and a set of quality data are necessary for carrying out this estimation exercise successfully.
Studies that confirm the existence of a greenium suggest that investors are willing to earn comparatively less on greener assets because they are hedging an environmental risk in various ways. Thus, lower (expected) returns for greener assets turn out to be by and large a consequence of their lower risk. However, at least in part it is also reflecting the shadow value of environmental concerns by market participants. This wedge between green and brown assets (risk-adjusted) performance—the essence of the green premium—can also be interpreted as a convenience yield associated to greener assets (expected) return.
While our analysis has focused largely on green assets versus brown assets, today’s policy debate increasingly focuses on transition assets, transition bonds, and transition plans. We know for a fact that many emissions-intensive sectors cannot become green immediately. This extension would require a proper Transition Finance Framework (TFF) to elaborate on the important question of how we should go about financing hard-to-abate sectors. Similarly, we have focused almost exclusively on mitigation-oriented finance. However, recent developments in green finance are also emphasising the role of adaptation bonds, resilience bonds, and climate-resilient infrastructure financing. This is increasingly relevant because adaptation investment needs are expanding rapidly.
One important limitation of this work is its focus on financial markets as the primary institutional mechanism for allocating capital toward sustainability. Current policy debate, as witnessed by the growing literature on institutional alternatives to purely market-based approaches, particularly the concept of Common Asset Trusts, tackles the deeper institutional question of whether markets are the appropriate governance mechanism for managing natural capital in the first place. Many ecosystem services are common-pool or public goods whose value cannot be adequately represented through asset prices alone. As a result, even a correctly priced greenium may still fail to produce socially optimal stewardship of natural capital 9. This perspective argues that critical natural capital should be managed as a common asset held in trust for current and future generations rather than primarily through private ownership and financial markets 10. Hence, the challenge is not limited on how markets price environmental assets, but also which institutions are best suited to govern natural capital. Incorporating this broader institutional perspective, going beyond financial markets, to the governance systems needed for long-term ecological sustainability is a subject that deserves to be taken up in future work.
Statement of the Use of Generative AI and AI-Assisted Technologies in the Writing Process
During the preparation of this manuscript, the author used Co-Pilot in order to improve the style of the exposition and check references. After using this tool, the author reviewed and edited the content as needed and takes full responsibility for the content of the published article
Ethics Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
Data is available on request.
Funding
This research received no external funding.
Declaration of Competing Interest
The author declares that they have no known competing financial interests or personal relationships that could have appeared to influence the work reported in this paper.
Footnotes
-
EMH asserts that asset prices should fully and immediately reflect all available information, leaving little or no room for systematic excess returns beyond risk exposure.
-
According to [15] the negative slope of the benchmark greenium term structure can reconcile the theoretical prediction of [6] with the average realized green excess returns documented by [17].
-
For example, key performance indicators (KPI) bonds such as sustainability-linked bonds do not have their proceeds set aside for any specific ESG purpose but rather reward (or penalize) the issuer by requiring lower interest payments to investors in the case that pre-agreed sustainability KPIs are met.
-
The Green Bond Principles (GBP), managed by the International Capital Market Association (ICMA), are voluntary global guidelines that promote transparency and integrity in the green finance market. They require issuers to align their debt instruments with four core components: Use of Proceeds, Project Evaluation and Selection, Management of Proceeds, and Reporting.
-
the Climate Bonds Initiative (CBI), for example, provides eligibility requirements and certification standards; assets meeting the CBI standard are eligible for Climate Bond Certification.
-
In the paper the performance of sustainable portfolios versus non-sustainable portfolios refers to the ESG score and the performance of green and brown portfolios to the E score.
-
I thank an anonymous referee for drawing my attention to the results of this paper.
-
MLP is feedforward artificial neural network featuring an input layer, one or more hidden layers, and an output layer connected by weighted nodes and nonlinear activation functions.
-
I owe this important observation to an anonymous referee.
-
Under this framework, markets remain useful for allocating rival, excludable goods, but stewardship of ecosystems requires governance institutions grounded in the public trust doctrine, common property rights, and Ostrom's principles for managing commons.
References
- Ferrer R, Benítez R, Bolós VJ. Interdependence between Green Financial Instruments and Major Conventional Assets: A Wavelet-Based Network Analysis. Mathematics 2021, 9, 900. DOI:10.3390/math9080900 [Google Scholar]
- Chen A, Chen Y, Nguyen T, Uddin GS. Goal-oriented preferences for green bonds: A model of sustainable investment strategies. Econ. Model. 2025, 150, 107128. DOI:10.1016/j.econmod.2025.107128 [Google Scholar]
- Larcker DF, Watts EM. Where’s the greenium? J. Account. Econ. 2020, 69, 101312. DOI:10.1016/j.jacceco.2020.101312 [Google Scholar]
- Baker M, Bergstresser D, Serafeim G, Wurgler J. Financing the Response to Climate Change: The Pricing and Ownership of U.S. Green Bonds; National Bureau of Economic Research: Cambridge, MA, USA, 2018; Working Paper n. 25194. [Google Scholar]
- Nederkoorn A, Scholten R. The Greenium in High-Rated Euro Bonds. Robeco Switzerland. 2024. Available online: https://www.robeco.com/en-ch/insights/2024/03/the-greenium-in-high-rated-euro-bonds (accessed on 31 July 2026).
- Pástor Ľ, Stambaugh RF, Taylor LA. Sustainable investing in equilibrium. J. Financ. Econ. 2021, 142, 550–571. DOI:10.1016/j.jfineco.2020.12.011 [Google Scholar]
- ICMA. Green Bond Principles: Voluntary Process Guidelines for Issuing Green Bonds; ICMA: Paris, France, 2018. [Google Scholar]
- Hachenberg B, Schiereck D. Are green bonds priced differently from conventional bonds? J. Asset Manag. 2018, 19, 371–383. DOI:10.1057/s41260-018-0088-5 [Google Scholar]
- Fandella P, Cociancich V. Uncovering the greenium: Investigating the yield spread between green and conventional bonds. Invest. Manag. Financ. Innov. 2024, 21, 56–69. DOI:10.21511/imfi.21(2).2024.05 [Google Scholar]
- Flammer C. Corporate green bonds. J. Financ. Econ. 2021, 142, 499–516. DOI:10.1016/j.jfineco.2021.01.010 [Google Scholar]
- Tang DY, Zhang Y. Do shareholders benefit from green bonds? J. Corp. Financ. 2020, 61, 101427. DOI:10.1016/j.jcorpfin.2018.12.001 [Google Scholar]
- Preclaw R, Bakshi A. The Cost of Being Green. Report, Barclays Credit Research. 2015. Available online: https://www.environmental-finance.com/assets/files/US_Credit_Focus_The_Cost_of_Being_Green.pdf (accessed on 31 July 2026).
- Löffler KU, Petreski A, Stephan A. Drivers of green bond issuance and new evidence on the “greenium”. Eurasian Econ. Rev. 2021, 11, 1–24. DOI:10.1007/s40822-020-00165-y [Google Scholar]
- Grzegorczyk M, Wolff G. Greeniums in Sovereign Bond Markets. Bruegel Working Paper 17/2022. 2022. Available online: https://www.econstor.eu/handle/10419/270471 (accessed on 31 July 2026).
- D’Amico S, Klausmann J, Pancost NA. The Benchmark Greenium. J. Financ. Econ. 2022, 176, 104217. DOI:10.2139/ssrn.4128109 [Google Scholar]
- Starks LT. Presidential address: Sustainable finance and ESG issues—Value versus Values. J. Financ. 2023, 78, 1837–1872. DOI:10.1111/jofi.13255 [Google Scholar]
- Pástor Ľ, Stambaugh RF, Taylor LA. Dissecting green returns. J. Financ. Econ. 2022, 146, 403–424. DOI:10.1016/j.jfineco.2022.07.007 [Google Scholar]
- Doronzo R, Siracusa V, Antonelli S. Green Bonds: The Sovereign Issuers’ Perspective; Infrastructures, Payment Systems, Working Paper No. 3; Banca d’Italia: Rome, Italy, 2021. [Google Scholar]
- Roch F, Brichetti JP, Cavallo EA. The Sovereign Greenium: Global Evidence and LAC Perspectives. Technical Note No Idb-Tn-3245. 2025. Available online: https://publications.iadb.org/en/sovereign-greenium-global-evidence-and-lac-perspectives (accessed on 31 July 2026).
- Ando S, Fu C, Roch F, Wiriadinata U. Sovereign Climate Debt Instruments: An Overview of the Green and Catastrophe Bond Markets; IMF Staff Climate Note 2022/004; International Monetary Fund: Washington, DC, USA, 2022. [Google Scholar]
- Ando S, Fu C, Roch F, Wiriadinata U. How Large is the Sovereign Greenium? Oxf. Bull. Econ. Stat. 2024, 86, 1472–1483. DOI:10.1111/obes.12619 [Google Scholar]
- Grishunin S. and Bukreeva A. In Search of Greenium. Analysis of Yields in the European Green Bond Markets. Procedia Comput. Sci. 2022, 214, 156–163. DOI:10.1016/j.procs.2022.11.161 [Google Scholar]
- Gianfrate G, Peri M. The green advantage: Exploring the convenience of issuing green bonds. J. Clean. Prod. 2019, 219, 127–135. DOI:10.1016/j.jclepro.2019.02.022 [Google Scholar]
- Zerbib O. The effect of pro-environmental preferences on bond prices: Evidence from green bonds Journal of Banking and Finance 2019, 98, 39, DOI:10.1016/j.jbankfin.2018.10.012. [Google Scholar]
- MacAskill S, Roca E, Liu B, Stewart RA, Sahin O. Is there a green premium in the green bond market? Systematic literature review revealing premium determinants. J. Clean. Prod. 2021, 280, 124491. DOI:10.1016/j.jclepro.2020.124491 [Google Scholar]
- Cioli V, Bianchini R, Giannozzi A, Roggi O. Does Greenium Exist? A Comparison between Sovereign and Corporate Bonds. Int. J. Bus. Manag. 2024, 19, 251. DOI:10.5539/ijbm.v19n6p251 [Google Scholar]
- Dragotto M, Dufour A, Varotto S. Greenium fluctuations and climate awareness in the corporate bond market. Int. Rev. Financ. Anal. 2025, 105, 104281. DOI:10.1016/j.irfa.2025.104281 [Google Scholar]
- Panizza U, Weder di Mauro B, Shi S, Gulati M. The Sovereign Greenium: Big Promise but Small Price Effect. Virginia Law and Economics Research Paper No. 2025-23. 2025. Available online: https://repository.graduateinstitute.ch/record/321543 (accessed on 31 July 2026).
- Bachelet MJ, Becchetti L, Manfredonia S. The Green Bonds Premium Puzzle: The Role of Issuer Characteristics and Third-Party Verification. Sustainability 2019, 11, 1098. DOI:10.3390/su11041098 [Google Scholar]
- Kapraun J, Latino C, Scheins C, Schlag C. (In)-Credibly Green: Which Bonds Trade at a Green Bond Premium? 2021. Available online: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3347337 (accessed on 31 July 2026).
- Meyer FA. Carbon Risk in European Equity Returns. Jr. Manag. Sci. 2022, 7, 429–454. DOI:10.5282/jums/v7i2pp429-454 [Google Scholar]
- Lopez De Prado M. In the View of a Carbon Tax: How Carbon Emission and Climate Change Action Are Priced in US Stocks. Master’s Thesis, Erasmus University Rotterdam, Rotterdam, The Netherlands, 2019. [Google Scholar]
- Oestreich AM, Tsiakas I. Carbon emissions and stock returns: Evidence from the EU Emissions Trading Scheme. J. Bank. Financ. 2015, 58, 294–308. DOI:10.1016/j.jbankfin.2015.05.005 [Google Scholar]
- Görgen M, Jacob A, Nerlinger M, Riordan R, Rohleder M, Wilkens M. Carbon Risk. 2020. Available online: https://ssrn.com/abstract=2930897 (accessed on 31 July 2026).
- Ferraboschi P, Muzzioli S. The Green Premium in the European Stock Market. DEMB Working Paper Series, N. 251. 2025. Available online: https://iris.unimore.it/handle/11380/1372628 (accessed on 31 July 2026).
- Monasterolo I, de Angelis L. Blind to carbon risk? An analysis of stock market reaction to the Paris Agreement. Ecol. Econ. 2020, 170, 106571. DOI:10.1016/j.ecolecon.2019.106571 [Google Scholar]
- Alessi L, Ossola E, Panzica R. When do investors go green? Evidence from a time-varying asset-pricing model. Int. Rev. Financ. Anal. 2023, 90, 102898. DOI:10.1016/j.irfa.2023.102898 [Google Scholar]
- Fanari M, Caccavaio M, Di Zio D, Letta S, Milano C. Is There an Equity Greenium in the Euro Area? Number 66 2025 Banca d’Italia, Markets, Infrastructures, Payment Systems working paper N. 66. Available online: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=6758538 (accessed on 31 July 2026).
- Bolton P, Kacperczyk M, Wang T. Energy Prices and the Carbon Premium. 2026. Available online: https://ssrn.com/abstract=4847591 (accessed on 31 July 2026).
- Engle RF, Giglio S, Kelly B, Lee H, Stroebel J. Hedging Climate Change News. Rev. Financ. Stud. 2020, 33, 1184–1216. DOI:10.1093/rfs/hhz072 [Google Scholar]
- Tsagkanos A, Mitropoulos IC. Volatility Risk, Climate Risk and Green Corporate Bond Pricing in Greece. Int. J. Financ. Econ. 2026, 31, 3631–3642. DOI:10.1002/ijfe.70110 [Google Scholar]
- Alessi L, Ossola E, Panzica R. What greenium matters in the stock market? The role of greenhouse gas emissions and environmental disclosures. J. Financ. Stab. 2021, 54, 100869. DOI:10.1016/j.jfs.2021.100869 [Google Scholar]
- Gagliardini P, Ossola E, Scaillet O. Time-Varying Risk Premium in Large Cross-Sectional Equity Data Sets. Econometrica 2016, 84, 985–1046. DOI:10.3982/ECTA11069 [Google Scholar]
- Chamberlain G, Rothschild M. Arbitrage, Factor Structure, and Mean-Variance Analysis on Large Asset Markets. Econometrica 1983, 51, 1281–1304. DOI:10.2307/1912275 [Google Scholar]
- Fama EF, French KR. Common risk factors in the returns on stocks and bonds. J. Financ. Econ. 1993, 33, 3–56. DOI:10.1016/0304-405X(93)90023-5 [Google Scholar]
- Raissi M, Darkaoui A, Admi S, Bouzid H. Deep Learning for the Greenium: Evidence from Green Bonds, Risk Disclosures, and Market Sentiment. J. Financ. Risk Manag. 2025, 18, 717. DOI:10.3390/jrfm18120717 [Google Scholar]
- Gu S, Kelly BT, Xiu D. Autoencoder Asset Pricing Models. Chicago Booth Working Paper No. 19-24. 2019. Available online: https://ssrn.com/abstract=3335536 (accessed on 31 July 2026).